What defines the Medical Loupes Market scope and structural role in modern healthcare?
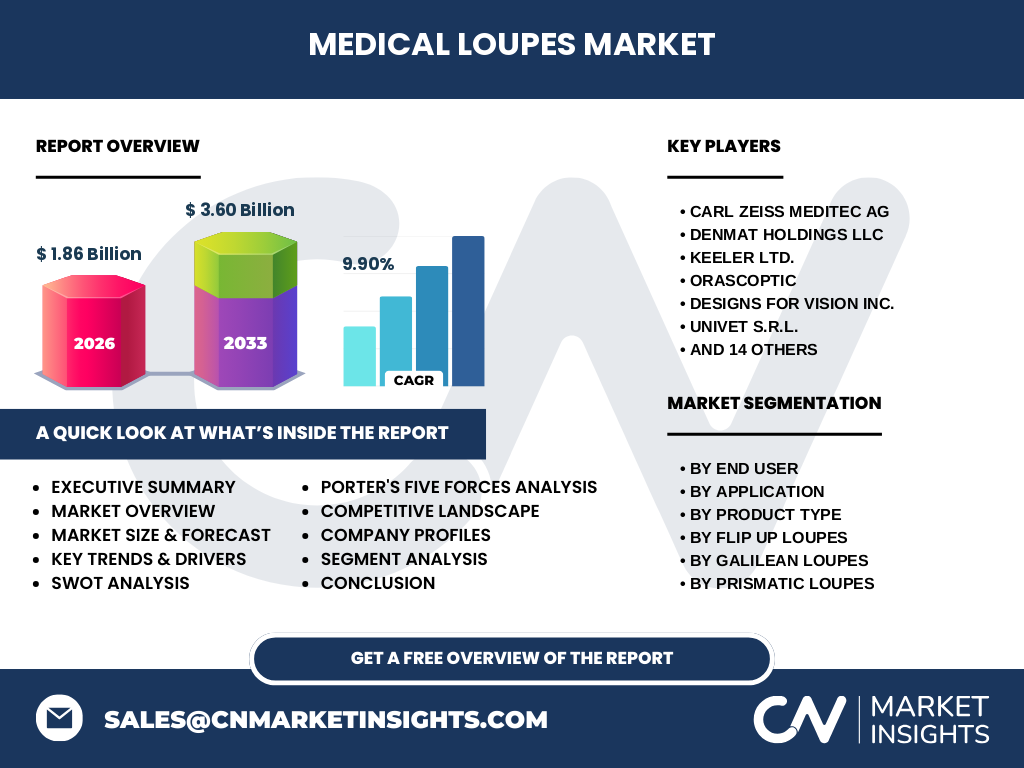
Our analysis indicates the Medical Loupes Market encompasses precision magnification optics utilized across surgical and dental suites to enhance ergonomic posture and visual acuity. Valued at 1.86 Billion in 2026, this sector forms a critical technological foundation for precision medicine, ensuring regulatory adherence under strict FDA and CE medical device frameworks.
Structural Growth Drivers and Market Constraints Shaping the Industry
Growth is propelled by rising volumes of minimally invasive procedures and heightened ergonomic awareness among surgeons, countered by high initial capital expenditures for custom-fit optics. Key industry participants like Carl Zeiss Meditec AG and Orascoptic constantly innovate to navigate these pricing and reimbursement hurdles across global healthcare systems.
The Shift Toward Advanced Ergonomic Illumination and Custom Optics
The market is witnessing an accelerated migration toward integrated LED lighting and lightweight frame designs. Designs for Vision Inc. and SurgiTel are pioneering customized focal lengths that mitigate occupational musculoskeletal disorders, fundamentally transforming procedural efficiency in high-acuity operating theaters.
Pandemic Aftershocks and Recovery Trajectory
The COVID-19 pandemic severely disrupted elective surgeries and global supply chains for optical glass and raw aluminum frames. However, our research confirms a robust post-pandemic recovery, driven by surgical backlog clearances and heightened infection control protocols mandating easily sterilizable, individual-use magnification systems.
Competitive Benchmarking and Market Concentration
The competitive landscape features a mix of multinational optical conglomerates and specialized dental optics specialists. Companies such as Keeler Ltd., Heine Optotechnik GmbH & Co. KG, and Univet S.r.l. maintain strong market shares through proprietary coating technologies and expansive global distribution networks.
Executive Summary: Key Findings in the Medical Loupes Market
The Medical Loupes Market is poised for exceptional expansion, driven by technological integration and rising surgical volumes. Our comprehensive report projects the market to reach 3.60 Billion by 2033, expanding at a robust CAGR of 9.90% from 2027 onward, presenting lucrative opportunities for strategic investors.
Long-Term Market Forecast from 2027 to 2033
Propelled by an accelerating CAGR of 9.90%, the market valuation will scale from 1.86 Billion in 2026 to 3.60 Billion by 2033. This trajectory reflects compounding adoption rates in emerging economies and continuous technological replacement cycles for aging optical inventory in mature hospital systems.
Segmentation Analysis: Product Types, Applications, and End Users
Market segmentation spans product types including Flip Up Loupes, Through The Lens Loupes, Prismatic Loupes, Galilean Loupes, and Headband Mounted Loupes. Applications cover surgical and dental procedures, while end users comprise hospitals, specialty clinics, and ambulatory surgical centers acquiring systems via direct sales and online channels.
Geographic Distribution and Regional Performance Dynamics
Regional performance varies significantly, with North America leading in revenue generation due to advanced healthcare infrastructure and stringent occupational health mandates. Meanwhile, Asia-Pacific represents the fastest-growing frontier, fueled by expanding private hospital networks and rising disposable incomes in medical tourism hubs.
In-Depth Regional Review and Regulatory Landscapes
North America and Europe dominate through high adoption of custom-fit optics governed by FDA and MDR compliance standards. Conversely, emerging markets in Latin America and APAC present unique logistical hurdles, favoring agile local distributors and manufacturers offering cost-effective Galilean and lightweight frame solutions.
Strategic Positioning of Leading Companies
Market leaders leverage distinct strategic advantages; for instance, Bryant Dental Ltd. and Admetec Solutions Ltd. focus on direct-to-consumer digital customization, whereas legacy giants like Seiler Instrument Inc. and Zumax Medical Co. Ltd. capitalize on bundled optical microscope and loupe contracts for institutional buyers.
Porter's Five Forces Analysis of the Optics Sector
Industry rivalry is intense, driven by continuous optical innovation and aggressive pricing from regional players. While supplier power over raw optical glass is moderate, buyer bargaining power is mitigated by the highly specialized, prescription-grade nature of custom-fit surgical loupes.
SWOT Analysis of the Medical Loupes Industry
Strengths lie in high-margin proprietary lens coatings and ergonomic designs; weaknesses involve steep manufacturing costs. Opportunities abound in integration with digital surgical navigation, while threats stem from unregulated low-cost imports bypassing stringent optical standards set by bodies like the FDA.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with optical glass and aerospace-grade aluminum sourcing, moving through precision grinding and anti-reflective coating application by innovators like Q-Optics LLC and LumaDent Inc. Finished goods flow through direct sales or specialized medical distributors to clinicians in hospitals and ambulatory centers.
Investment Insights and High-Potential Areas
High-potential investment pockets center on integrated LED illumination optics and AI-assisted digital fitting platforms. Venture capital and private equity should target agile innovators like Xenosys Co. Ltd. and ExamVision ApS that demonstrate strong intellectual property portfolios in lightweight prism technology.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Medical Loupes Market offers compelling growth, backed by a clear trajectory toward 3.60 Billion by 2033. Stakeholders must prioritize ergonomic innovation and digital customization channels to capture market share in an increasingly competitive global healthcare ecosystem.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with chief surgeons and procurement officers, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in market sizing and growth rate projections.
Scope of the Report and Analytical Parameters
This report covers global revenue performance, volume shipments, and strategic shifts across all specified product categories and end-user segments from 2026 to 2033. Macroeconomic currency fluctuations and localized healthcare reimbursement policy changes represent the primary analytical boundary limitations.
Recent Developments, Partnerships, and Product Launches
Recent industry momentum highlights strategic collaborations, such as new product rollouts by SheerVision Inc. and Rose Micro Solutions LLC focusing on wireless LED integration. These moves underscore a broader industry race toward untethered, lightweight ergonomic solutions for modern surgical teams.